Inventory financing is short-term funding that lets a business buy stock now and repay as that stock sells. The lender advances money against the value of the inventory you buy or already hold, so you can meet demand, stock up before peak season, or take on a large order without draining cash reserves.
This guide explains how inventory financing works, the main types, what it costs, who qualifies, and how to apply for an inventory financing loan.
What Is Inventory Financing?
Inventory financing is a form of asset-based lending in which inventory serves as the basis for a loan or line of credit. Retailers, wholesalers, distributors, importers, and manufacturers use it to buy goods before they have the cash from selling them.
How it typically works:
- The lender values your inventory. It looks at what you sell, how quickly it turns over, and how easily it could be resold.
- You receive an advance. Lenders usually fund a percentage of the inventory's value rather than the full amount, since stock can lose value or sell slowly.
- You buy and sell the goods. The funds go toward purchasing stock, often paid directly to your supplier.
- You repay from sales. As the inventory sells, you repay the advance plus interest and fees, either on a fixed schedule or by drawing and repaying a revolving line.
Inventory financing is different from accounts receivable financing, which advances cash against invoices you have already issued rather than goods you hold.
Types of Inventory Financing
| Type | How it works | Best for | Collateral |
|---|---|---|---|
| Inventory loan | A lump sum to buy stock, repaid over a fixed short term | A single large or seasonal purchase | The inventory purchased |
| Inventory line of credit | A revolving limit you draw on for stock and repay as goods sell | Ongoing, repeat inventory purchases | Inventory, sometimes plus receivables |
| Warehouse / asset-based financing | A borrowing base tied to inventory held in a warehouse | Distributors and wholesalers with large stock | Warehoused inventory |
| Purchase order financing | Pays your supplier to fulfill a confirmed customer order | Large orders you can't fund upfront | The customer order, not existing stock |
| Vendor financing | A financier pays your supplier now and you repay later | Importers and resellers who want longer payment terms | Often collateral-free |
| Floor plan financing | A revolving line for high-value units, repaid as each unit sells | Dealers of vehicles, equipment, and appliances | The individual units |
If your inventory is tied to a specific customer order, purchase order financing is usually a better fit. If you want to pay overseas or domestic suppliers later without pledging stock, consider vendor financing. For a deeper breakdown, see our guide to the types of inventory financing.
How Much Does Inventory Financing Cost?
There is no single rate. Cost depends on the type of financing, the lender, your sales history, how quickly your inventory turns, and how easily it could be resold. Inventory-backed financing is often priced higher than a traditional bank loan because inventory can lose value, but it is usually faster and easier to qualify for.
When comparing offers, look at:
- Interest rate or factor rate, and whether it is charged monthly or annually
- Advance amount, as a share of inventory value
- Fees, including origination, monitoring, or audit fees
- Repayment terms and any penalties for early or late repayment
Read more in our guide to comparing inventory financing rates.
Who Qualifies for Inventory Financing?
Lenders focus on the quality of your inventory and your ability to sell it. You are a stronger candidate if you have:
- Sellable, non-perishable inventory with steady demand
- A track record of sales, usually at least a year in business
- Accurate inventory records and financial statements
- Healthy turnover, showing stock does not sit for long
- Reasonable business credit, though asset-based lenders weigh it less than banks
Why Businesses Use Inventory Financing
- Manage cash flow: Keep cash available for payroll, rent, and other operating costs while still restocking.
- Prepare for peak season: Build stock ahead of holiday or seasonal demand.
- Launch new product lines: Fund the first inventory for new products without waiting for profits.
- Meet sudden demand: Avoid stockouts and lost sales when orders spike.
- Buy in bulk: Take advantage of supplier volume discounts.
Prefer not to pledge your inventory? Drip Capital funds inventory purchases with collateral-free working capital of up to $3M, with funds in 24–48 hours and 30–90 day repayment terms. Check your eligibility
Advantages and Disadvantages of Inventory Financing
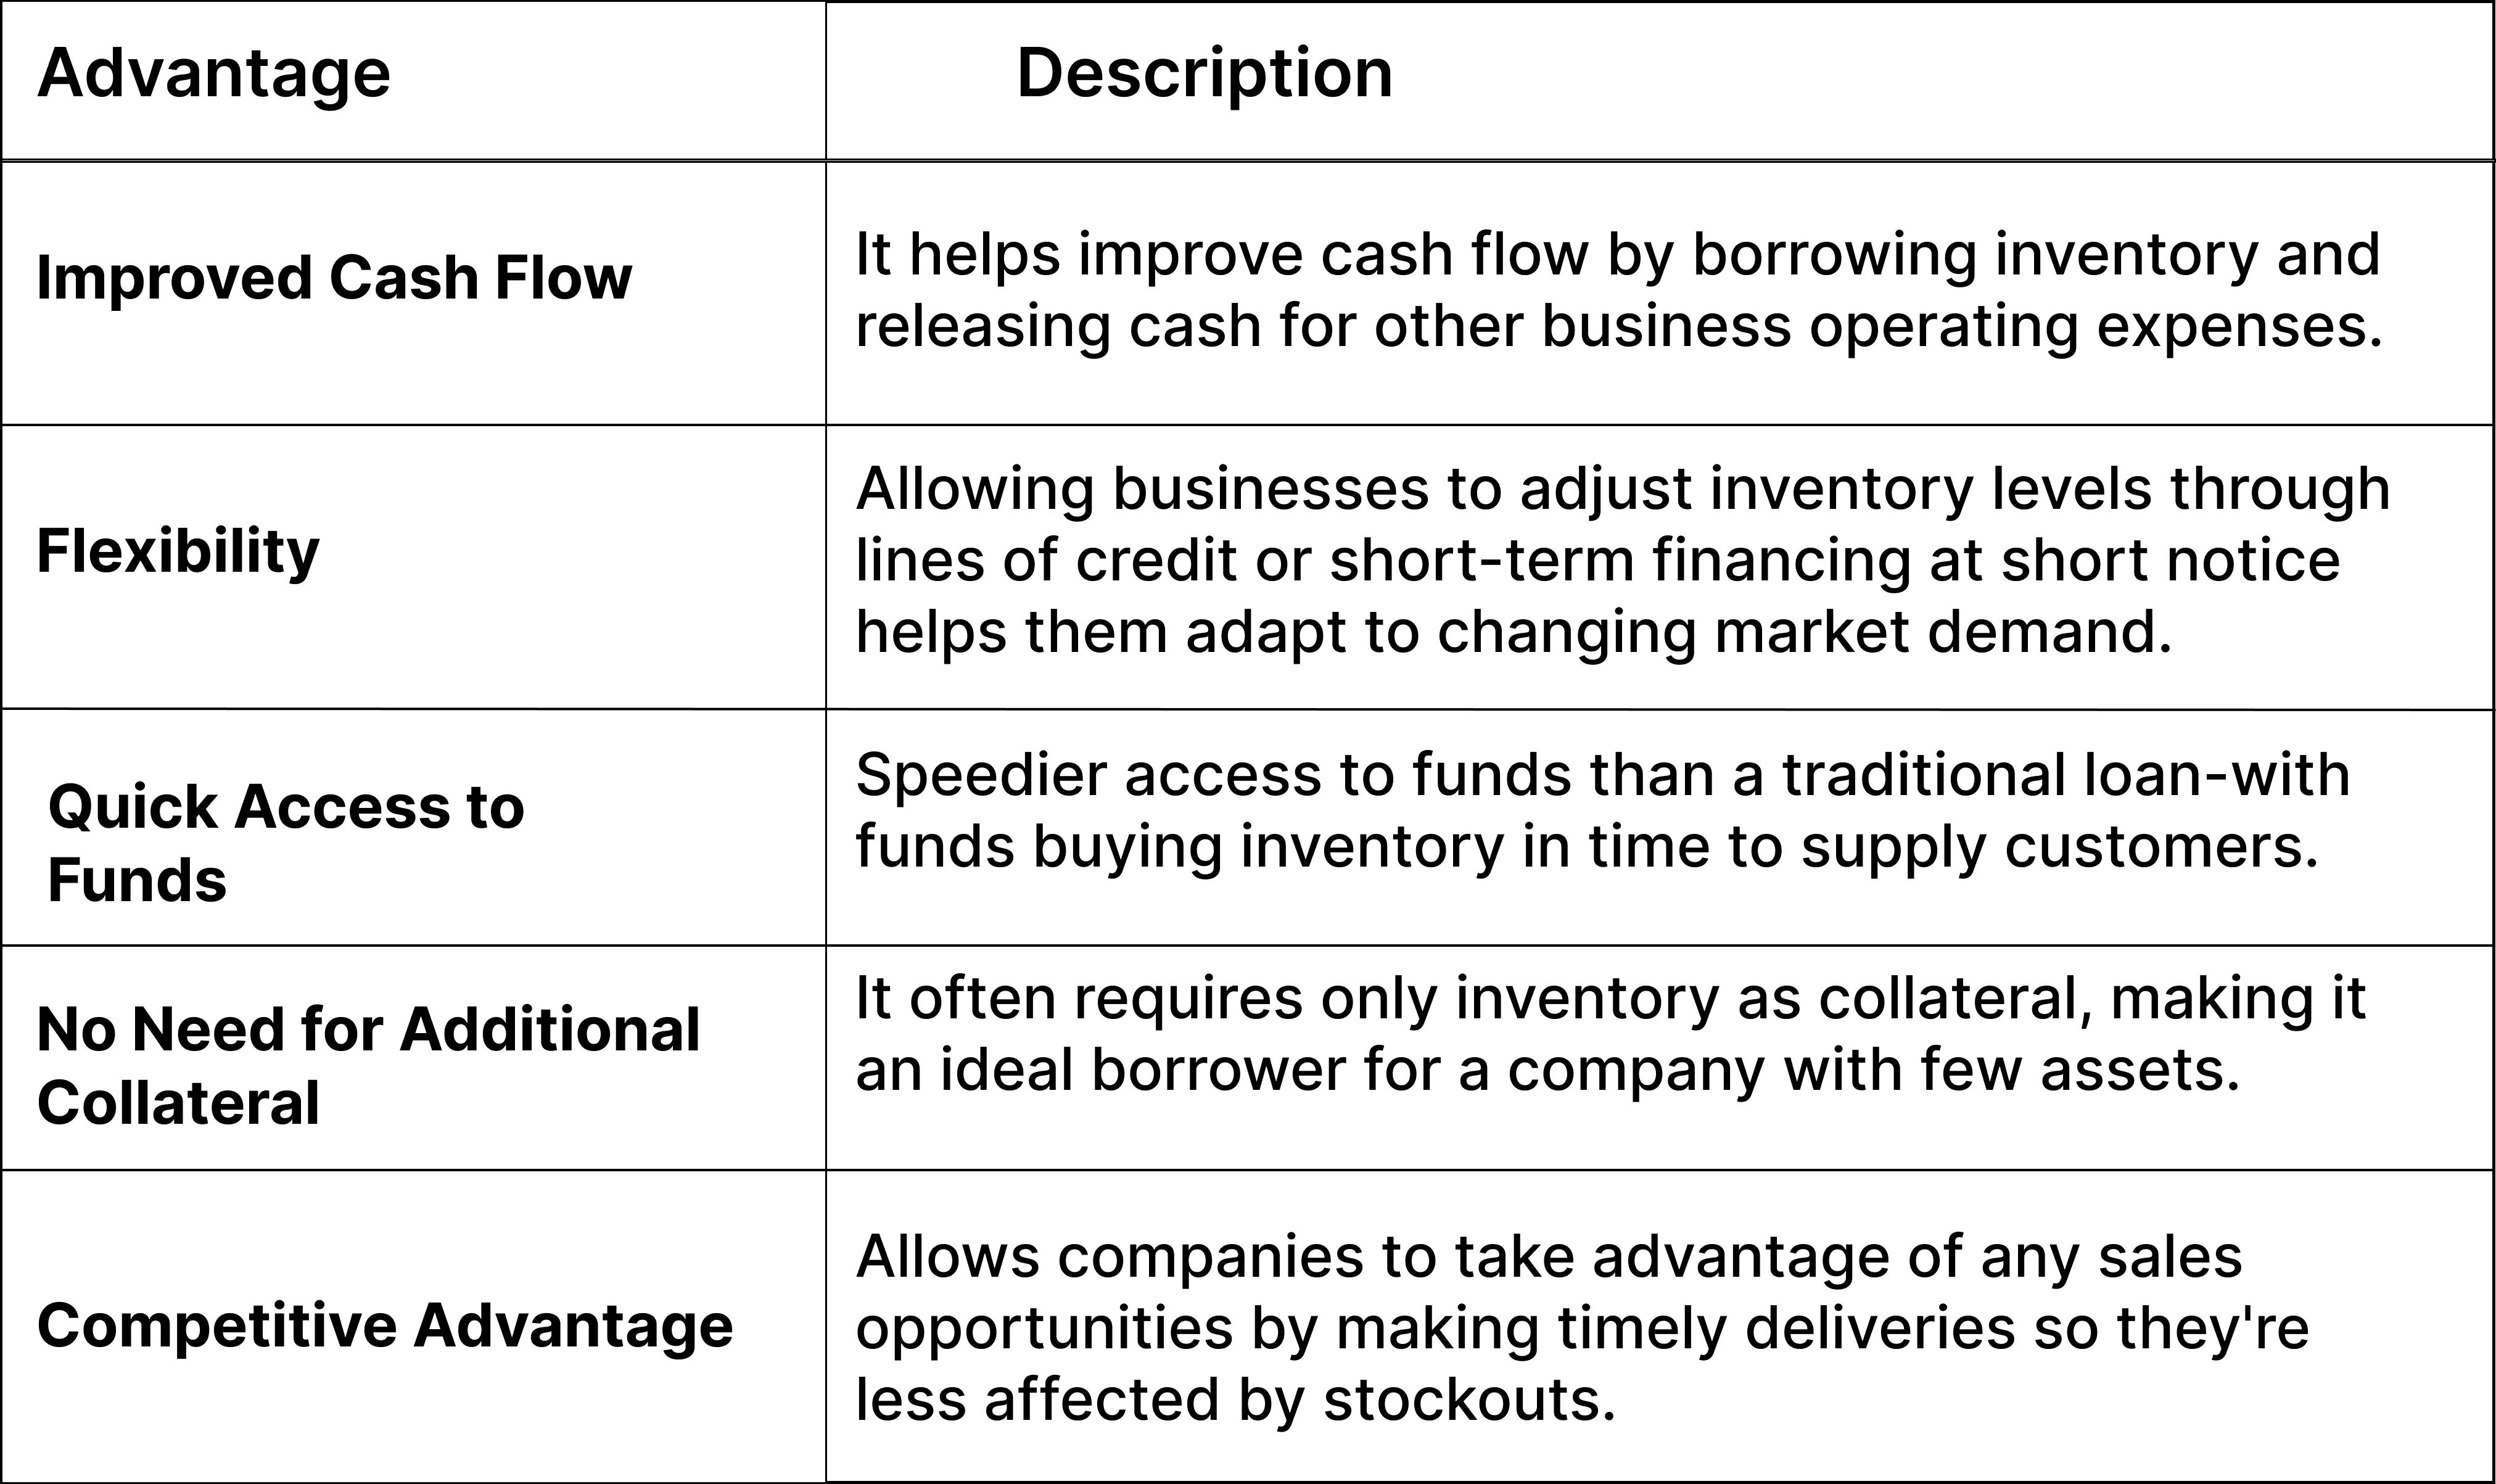
Advantages:
- Funds stock purchases without draining cash reserves
- Easier to qualify for than many unsecured bank loans
- Scales with your inventory and sales
- Helps you capture seasonal demand and bulk discounts
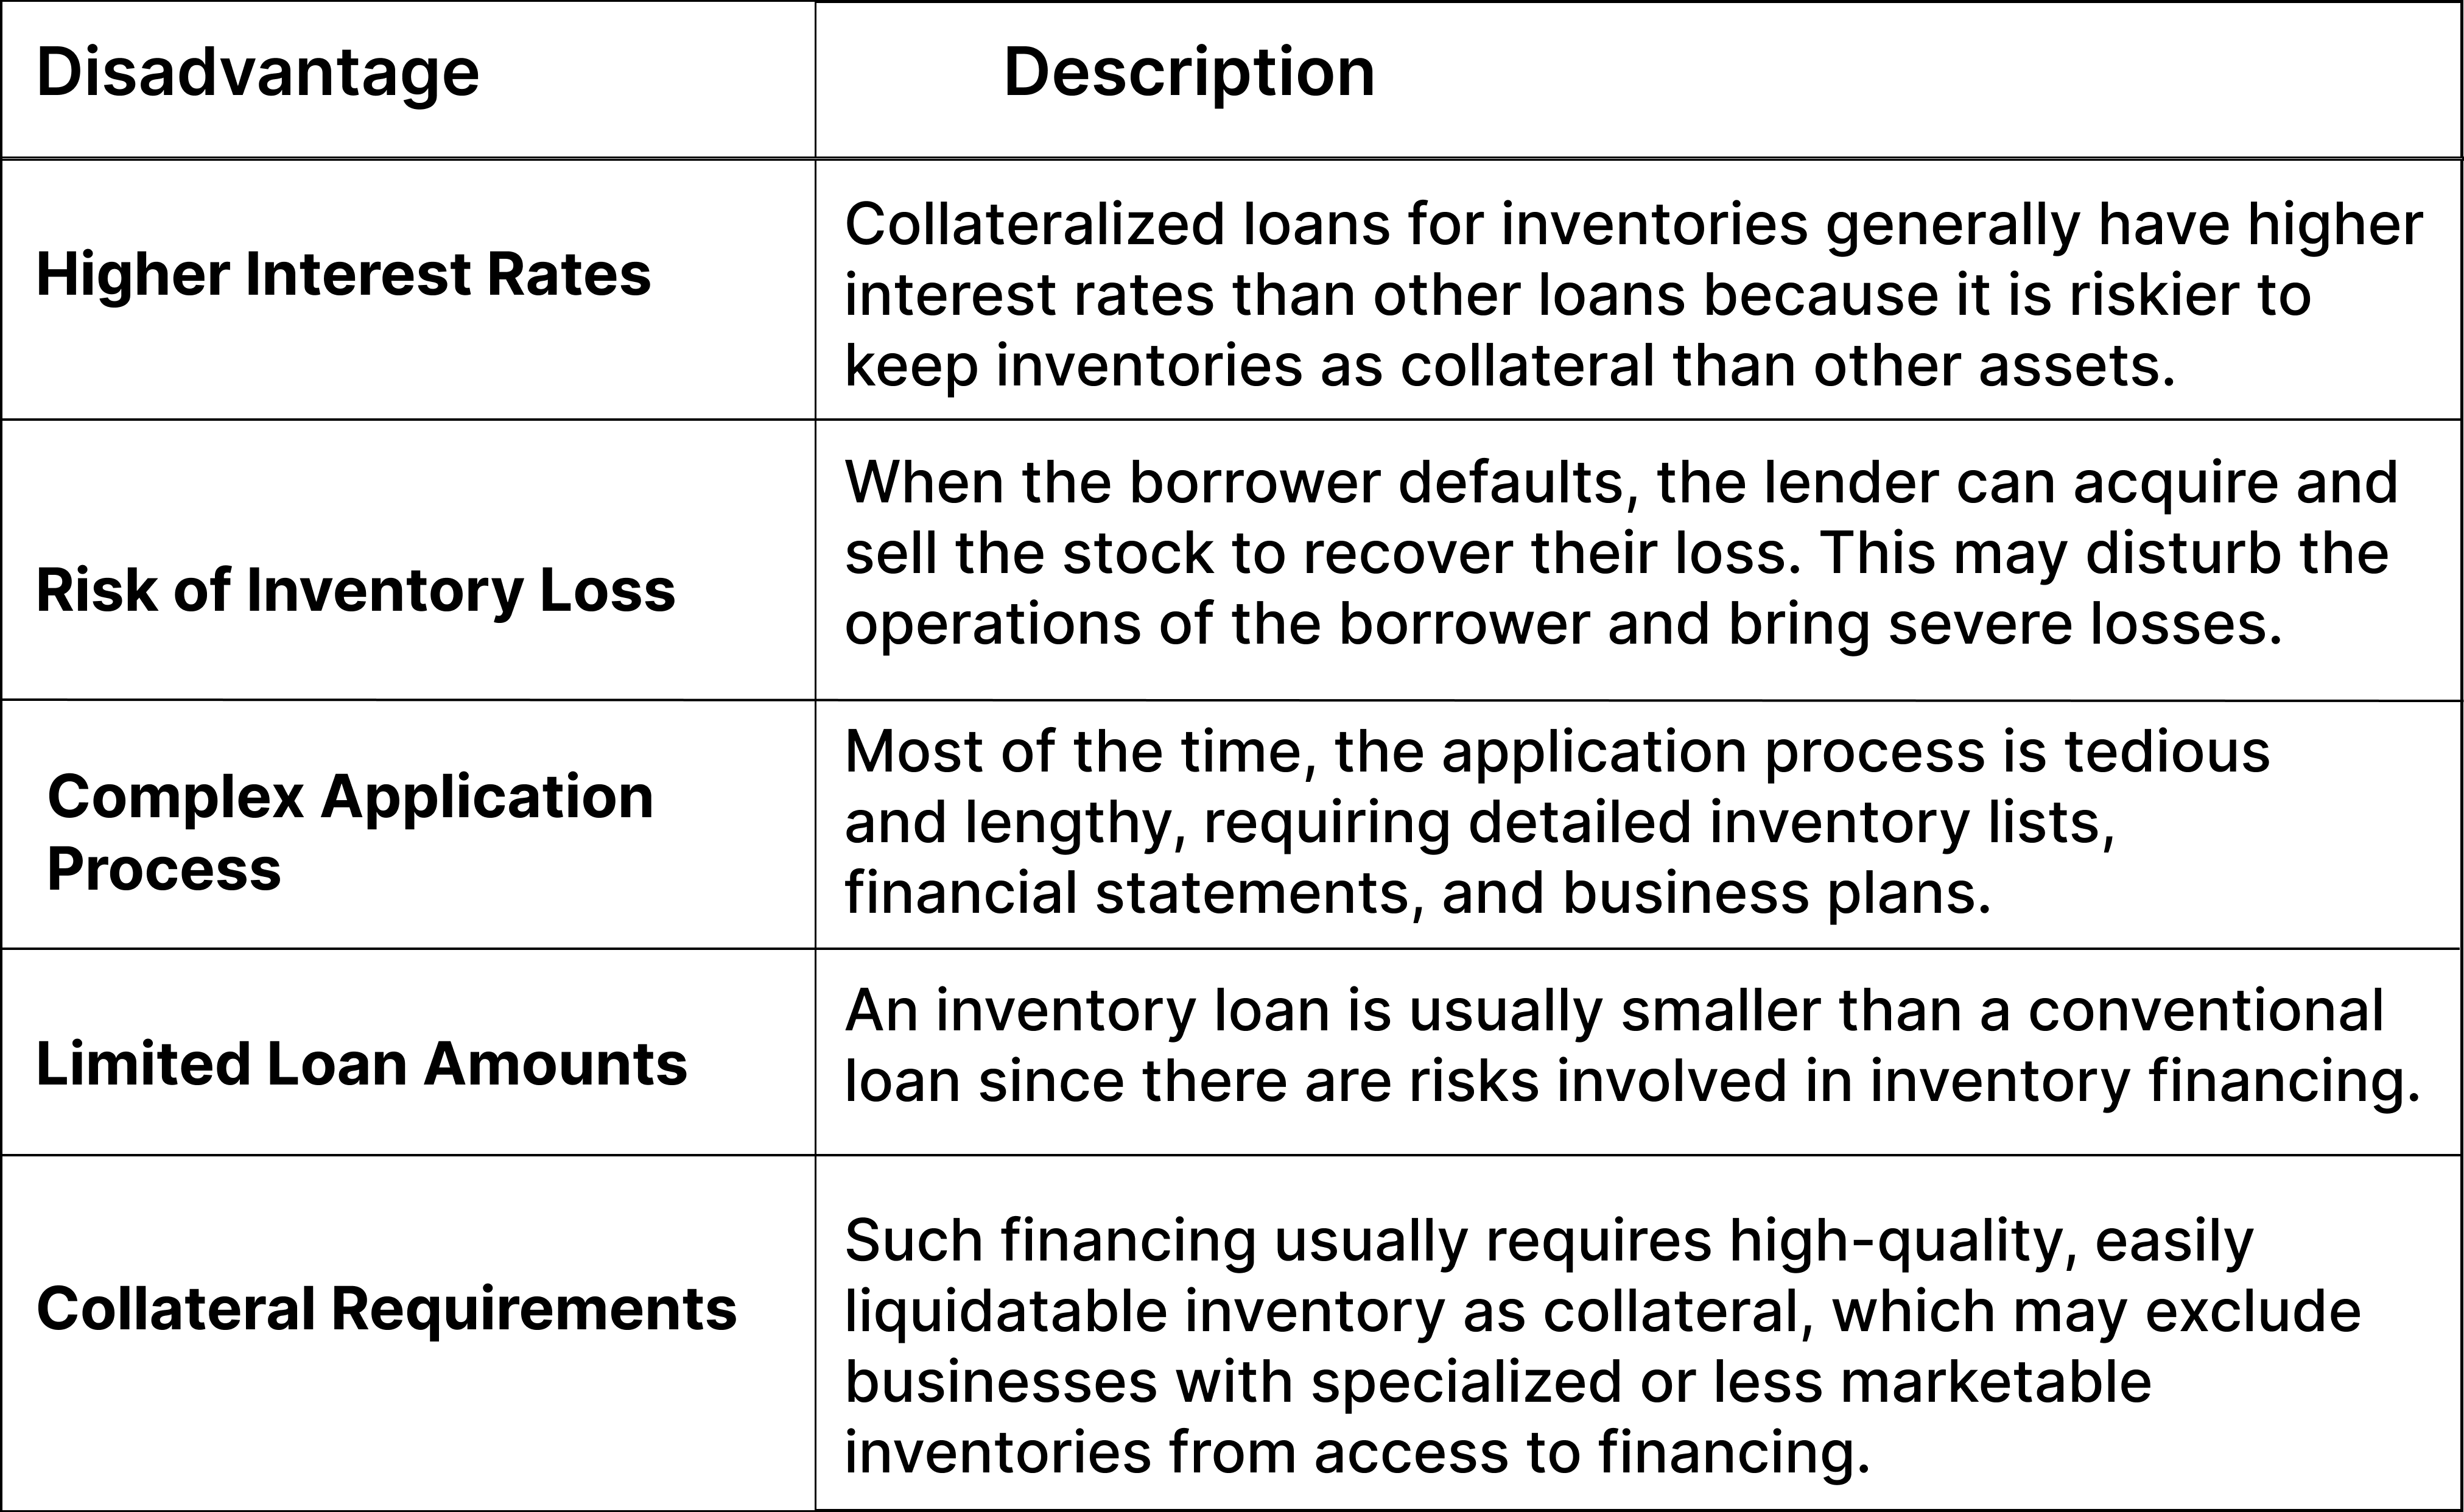
Disadvantages:
- Often more expensive than traditional bank financing
- Lenders usually advance only part of the inventory's value
- Slow-moving or perishable stock can be hard to finance
- Your inventory is at risk if you can't repay
How to Apply for Inventory Financing
- Value your inventory. Run an inventory count and valuation so you know how much you can realistically borrow.
- Choose the right type. Match the product to your need: a loan for a one-off purchase, a line of credit for ongoing stock, or PO or vendor financing for order-specific purchases.
- Compare lenders. Look at rates, fees, advance amounts, speed, and experience in your industry.
- Prepare your documents. Lenders typically ask for an inventory list, recent financial statements, sales history, and supplier details.
- Apply and receive funds. Once approved, funds are often paid directly to your supplier or released for stock purchases.
Inventory financing is an effective tool for businesses that want to keep stock levels healthy without straining cash flow. Understanding the types, costs, and trade-offs helps you choose the option that fits how your business buys and sells. For more options, see the best inventory financing options in 2026.
Disclaimer: This analysis is for informational purposes only and should not be used to make financial or legal decisions.
Frequently Asked Questions
1. What is the interest rate for inventory financing?
Rates vary by lender and borrower. They depend on your financial history, the type and value of your inventory, and how quickly it sells. Inventory financing is generally priced higher than traditional bank loans because lenders take on more risk.
2. Can I get an inventory loan with no credit history?
Some lenders offer inventory financing to businesses with limited credit history, focusing more on the inventory and sales. Expect higher costs and stricter terms than for established businesses.
3. Which businesses benefit from inventory financing?
Small and mid-sized retailers, wholesalers, distributors, importers, and manufacturers that buy inventory ahead of sales benefit most, especially businesses with seasonal demand or sudden spikes in orders.
4. What is the difference between inventory financing and purchase order financing?
Inventory financing funds stock you plan to sell or already hold. Purchase order financing funds the supplier costs for a specific, confirmed customer order, so approval depends on that order rather than on your existing inventory.
5. Can I get inventory financing without collateral?
Traditional inventory loans use the inventory as collateral. Some alternatives, such as vendor financing from Drip Capital, provide collateral-free funding to pay suppliers, with repayment terms of 30 to 90 days.
6. What are the alternatives to inventory financing?
Alternatives include business lines of credit, purchase order financing, vendor financing, invoice factoring, and traditional bank or SBA loans. Compare costs, speed, and collateral requirements before choosing.